What Cancellation Insurance Covers on a Hunt
You've been planning this hunting trip for months, maybe even years. The dates are circled, the gear is prepped, and the excitement is building. Then, out of nowhere, life throws a curveball: a sudden illness, a family emergency, or an unforeseen travel disruption. The thought of losing all that hard-earned money – the outfitter deposit, the flight tickets, the non-refundable licenses – is enough to make any hunter's stomach drop. This guide is here to shed some light on hunt cancellation insurance, explaining what it typically covers and, just as importantly, what it doesn't, so you can protect your investment and hunt with peace of mind.
Understanding the Basics of Hunt Cancellation Insurance
Embarking on a hunting adventure, especially one involving an outfitter, travel, and specialized permits, is a significant financial commitment. It's not just about the thrill of the chase; it's about the planning, the anticipation, and the hard-earned money you've invested. That's where hunt cancellation insurance comes into play, acting as a crucial safety net.
What is Hunt Cancellation Insurance, Really?
At its core, hunt cancellation insurance is a specialized form of travel insurance designed specifically for the unique needs of hunters. Think of it as a protective shield for your financial outlay against unforeseen circumstances that could force you to cancel or cut short your planned hunting expedition. It's meant to reimburse you for non-refundable expenses like outfitter deposits, guide fees, airfare, accommodation, and even the cost of non-transferable hunting licenses if your trip is derailed by a covered reason.
It's absolutely vital to understand that this isn't a blanket "get out of jail free" card for any reason you might decide not to go. Policies are built around specific, defined events. If your reason for canceling isn't explicitly listed as a covered peril in your policy document, then you won't be reimbursed. There's also a more comprehensive, but pricier, option called "cancel for any reason" (CFAR) insurance. This add-on, usually purchased within a short window after your initial deposit, offers the most flexibility, allowing you to cancel for reasons not typically covered by standard policies, often reimbursing a significant percentage (e.g., 75%) of your non-refundable costs. However, it's not always available and comes at a premium.
Why Hunters Need This Protection
The financial stakes in hunting can be incredibly high. A guided hunt in Alabama, particularly for a trophy whitetail or a coveted turkey, often requires a substantial upfront deposit, with the full balance due well in advance of the season. Airfare, rental cars, special gear purchases, and non-refundable permits like those for Alabama Hunting Licenses and What They Cost quickly add up. If you've been dreaming of a Booking a Black Belt Quail Plantation Hunt or a What a Guided Alabama Deer Hunt Costs, you know these aren't cheap endeavors.
Consider a scenario: you've booked a prime week for Alabama's Gun Deer Season by Zone with a reputable outfitter in the Black Belt, paying a hefty non-refundable deposit. Two weeks before your departure, your child suddenly falls ill and requires your full attention. Without cancellation insurance, that deposit, and any other non-refundable expenses you've incurred, could be gone forever. Or perhaps a severe weather event grounds all flights to your destination, making it impossible to arrive for the start of your hunt. These aren't just minor inconveniences; they represent real, tangible financial losses that can be incredibly frustrating and disheartening. Hunt cancellation insurance provides a safeguard, allowing you to recover a significant portion of those losses and potentially reschedule your adventure without breaking the bank.
Common Covered Reasons for Cancellation
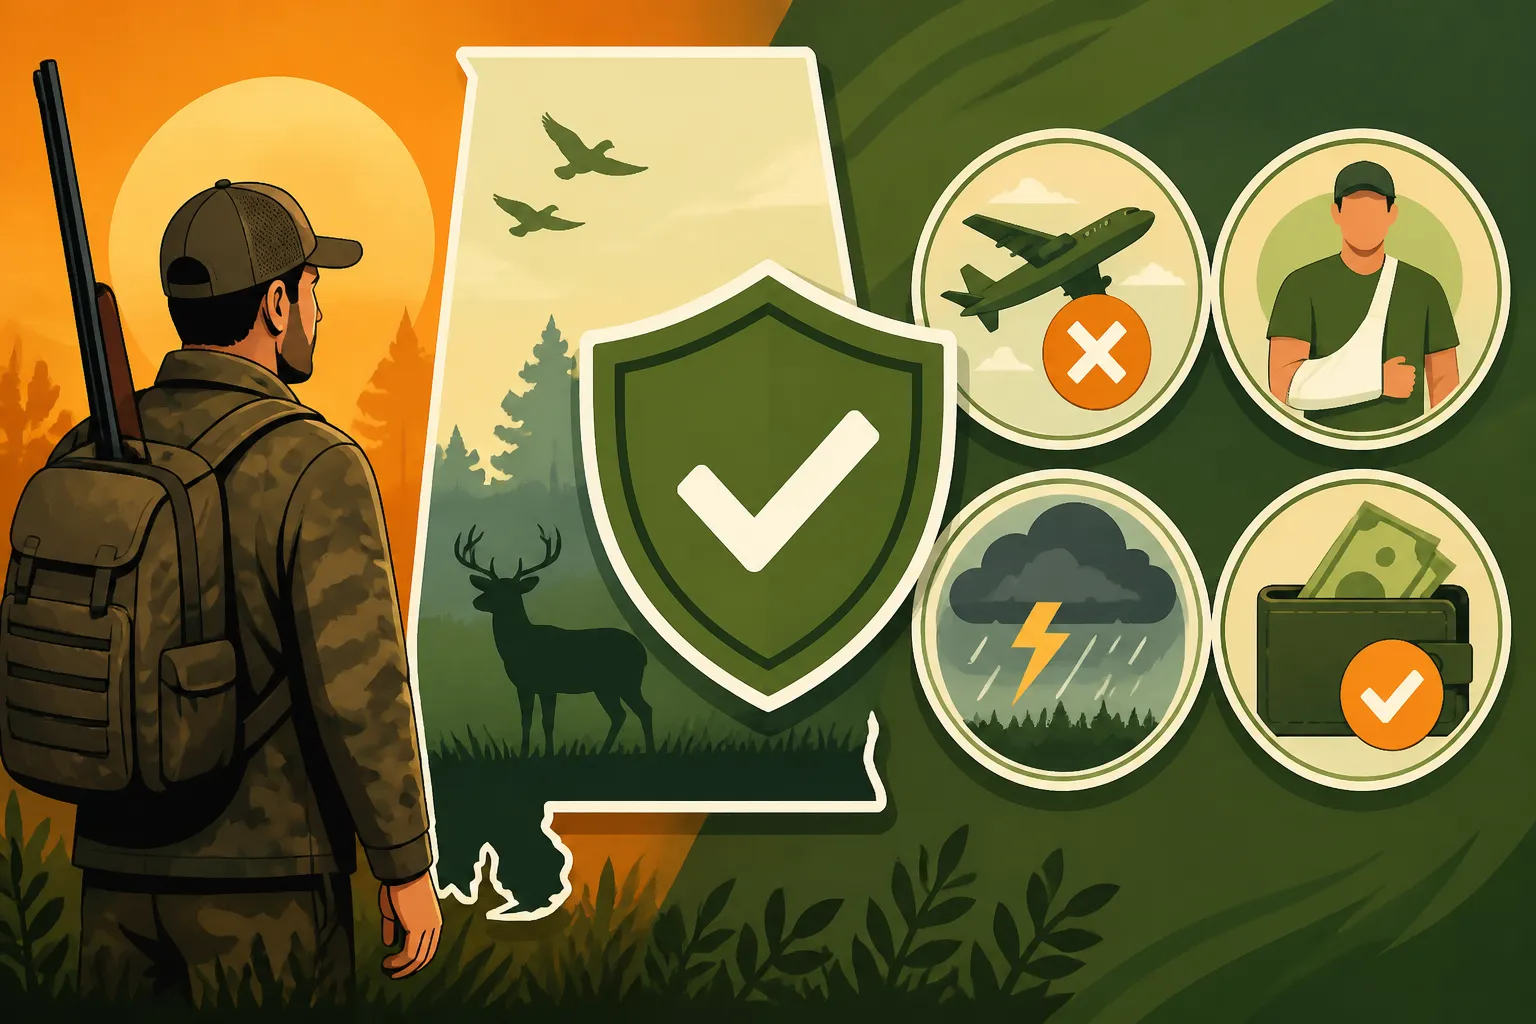
Most standard hunt cancellation policies are designed to protect you from a range of unpredictable events that are beyond your control. These fall broadly into personal emergencies, issues with your outfitter, and major travel disruptions.
Personal Emergencies and Health Issues
This is often the most critical coverage for hunters, as personal life events are inherently unpredictable. Policies typically cover situations where you, a traveling companion, or an immediate family member experiences a sudden, serious illness or injury that prevents you from going on or continuing your hunt. This isn't just a minor cold; we're talking about something medically significant that requires professional treatment and renders you unable to travel or participate in strenuous activity.
For example, imagine you've been training all year for an archery hunt for White-Tailed Deer Across Alabama, but a week before your trip, you suffer a debilitating back injury. Your doctor confirms you're unfit for travel or hunting, and suddenly, your carefully planned trip is in jeopardy. Or perhaps you receive news of a death in your immediate family, necessitating your presence elsewhere. Even an unexpected job loss that directly impacts your ability to afford or justify the trip can sometimes be a covered reason. These are the kinds of life disruptions that, while deeply unfortunate, are precisely what cancellation insurance is designed to protect against, ensuring that you don't suffer a double blow of personal hardship and financial loss.
Outfitter or Guide-Related Issues
While you should always practice due diligence when selecting an outfitter, as discussed in Vetting an Alabama Outfitter Before You Book, sometimes things happen that are beyond anyone's control. What if, after you've paid your deposit, your chosen outfitter suddenly declares bankruptcy or goes out of business? Or perhaps your specific guide, who you booked months in advance, suffers a serious injury and can no longer lead your hunt, and the outfitter can't provide a suitable replacement?
Many policies will cover the financial loss in such scenarios. This is particularly valuable because outfitter contracts often have very strict non-refundable clauses. It’s also important if an outfitter is forced to cancel the entire operation due to unforeseen circumstances, such as a natural disaster rendering their hunting grounds inaccessible or unsafe. However, be mindful that "outfitter-related issues" usually don't extend to things like simply having a bad year for game numbers or the outfitter deciding to change their hunting strategy that you don't agree with. The cancellation has to be a direct, severe disruption to the outfitter's ability to host the hunt as agreed.
Travel Disruptions and Natural Disasters
Getting to your hunting destination, especially if it's across state lines or involves multiple connections, can be a journey in itself. Travel cancellation can be a significant concern. Policies often cover cancellations due to severe weather events that cause common carriers (like airlines) to cease operations, making it impossible for you to reach your departure point or destination. This could be a major blizzard up north preventing your flight to Birmingham, or a hurricane impacting the Gulf Coast that closes access to areas for Coastal Alabama River Swamps hunting.
Furthermore, natural disasters directly impacting the hunting area itself can be covered. If the area you planned to hunt is suddenly engulfed by wildfires, or a severe flood makes it impossible to access or safely hunt, your policy might kick in. It’s important to note the distinction here: "severe weather preventing travel" is often covered, whereas "bad hunting weather" (e.g., a warm spell during a deer hunt or too much rain for turkeys) is typically not. Your policy protects against the inability to get there or access the area, not against less-than-ideal hunting conditions once you arrive.
| Covered Reason Categories | Examples of What's Typically Covered |
|---|---|
| Personal & Health | Hunter's or family member's serious illness/injury, death in family, job loss |
| Outfitter Issues | Outfitter bankruptcy/closure, guide injury/cancellation without replacement |
| Travel Disruptions | Severe weather halting common carrier travel, natural disaster rendering destination inaccessible |
| Trip Interruption | Emergency return home for covered reasons, emergency medical evacuation |
What's Typically Not Covered (and Why it Matters)
While hunt cancellation insurance provides vital protection, it's equally important to understand its limitations. Many hunters assume a policy will cover anything that makes their trip less enjoyable, but that's rarely the case. Knowing what's excluded can prevent significant disappointment and financial surprise.
Disappointment and Poor Hunting Conditions
This is perhaps the biggest point of misunderstanding for many hunters. Standard cancellation insurance policies are not designed to protect you from a hunt that simply doesn't live up to your expectations. This means if you arrive for your Spring Turkey Hunting in Alabama trip, and the gobblers are tight-lipped due to unusually high pressure or unseasonably warm weather, you cannot cancel your trip and expect reimbursement because the hunting is "slow." The same goes for a deer hunt where the bucks aren't moving, or a waterfowl trip where the ducks simply haven't shown up in numbers.
Insurance companies are protecting against financial loss due to unforeseen and unavoidable events that prevent the hunt from happening at all, not the quality of the hunting experience itself. You're paying for the opportunity to hunt, not a guaranteed harvest or a specific experience level. This distinction is critical and often surprises hunters who believe their policy covers "bad luck" in the field. If you simply decide you're not having fun, or the conditions aren't ideal, that falls outside the scope of typical coverage.
Exclusions and Pre-Existing Conditions
Like all insurance products, hunt cancellation policies come with a list of exclusions – specific situations or circumstances under which benefits will not be paid. These can vary widely between providers, so reading the fine print is paramount. Common exclusions might include acts of war, civil unrest, or travel to destinations under a government advisory (e.g., certain countries during a pandemic). Policies often exclude claims arising from your own reckless behavior or illegal activities.
Pre-existing medical conditions are another major area of exclusion. If you have a medical condition that existed before you purchased the policy, and that condition leads to your cancellation, it might not be covered. To get coverage for pre-existing conditions, you usually need to purchase your policy within a very short window (often 10-14 days) of your initial trip deposit and sometimes meet other eligibility requirements, like being medically able to travel at the time of purchase. Failing to disclose a pre-existing condition, or waiting too long to buy your policy, could invalidate your claim if that condition later forces you to cancel. It's crucial to be honest and thorough when applying for coverage.
Specific Hunting-Related Exclusions
Beyond general exclusions, some policies have specific clauses related to hunting that are important to note. For instance, most standard policies do not cover cancellation if you fail to draw a specific tag or license. If your dream hunt requires a special quota tag in a Alabama WMA Quota Hunt Sign-In Process, and you don't get selected in the draw, that's typically not a covered reason for canceling your associated travel and outfitter costs. There might be specialized riders or "draw insurance" available from some providers, but it's not standard.
Similarly, changes in hunting regulations after you've booked your trip, such as a modification to Alabama Antler Point Restriction Rules or season dates, are generally not covered. While frustrating, the opportunity to hunt still exists, even if the rules have changed. The policy covers your inability to take the trip, not your dissatisfaction with the legal parameters of the hunt. Finally, and this should go without saying, the policy won't cover you if you fail to harvest an animal, get cold feet, or simply change your mind about hunting. It's about protecting your financial investment against specific, defined risks, not guaranteeing a successful or enjoyable outing.
Choosing the Right Policy and Making a Claim
Navigating the world of insurance can feel daunting, but with a bit of research and understanding, you can find the right protection for your hunting investment.
Researching Providers and Policy Types
The first step is to recognize that not all travel insurance is created equal, and not all policies are equally suited for hunting trips. While major travel insurance companies offer general policies, some providers specialize in, or at least offer specific riders for, adventure travel and sporting pursuits. When researching, pay close attention to the policy wording regarding "activities" and "equipment" to ensure hunting is covered. Look at the benefit limits for trip cancellation, interruption, and emergency medical treatment or evacuation.
You'll want to compare deductibles, which is the amount you pay out-of-pocket before the insurance kicks in. Also, consider any "cancel for any reason" (CFAR) options if that flexibility is important to you, keeping in mind the higher cost and specific purchase windows. Some hunters might even check if their outfitter or booking platform (like BookYourHunt or GoHunt, where you might find guides listed) recommends specific insurance partners or if they offer any embedded insurance options. Remember, the cheapest policy isn't always the best; value lies in adequate coverage for your specific trip's risks. Be thorough, ask questions, and don't hesitate to get quotes from several providers to see what What Cancellation Insurance Covers on a Hunt really entails for your unique situation.
When and How to Purchase
Timing is often critical when it comes to purchasing hunt cancellation insurance. For the most comprehensive coverage, including pre-existing medical conditions and "cancel for any reason" benefits, you'll typically need to buy your policy within a very specific timeframe after making your initial deposit for the hunt. This window is commonly 10 to 21 days, depending on the provider. Missing this window might mean you can still buy a policy, but you could forfeit crucial benefits. Don't wait until the last minute, or just before your hunt, as many significant benefits become unavailable closer to the departure date.
When purchasing, you'll need to provide accurate information about your trip, including costs, dates, and destination. Keep meticulous records of all your hunt-related expenses: outfitter contracts, deposit receipts, flight confirmations, hotel bookings, and any other non-refundable payments. These documents will be vital if you ever need to file a claim. Be prepared to share your medical history, especially if seeking coverage for pre-existing conditions. Transparency upfront ensures a smoother claims process later.
The Claims Process
Should the unfortunate happen and you need to cancel or interrupt your hunt, initiating the claims process promptly is key. The first step is usually to notify your insurance provider immediately upon realizing you need to cancel. Many policies have strict notification requirements. You'll also want to inform your outfitter or guide as soon as possible, especially concerning their own Deposits and Cancellation Terms in Alabama.
Next, gather all supporting documentation. This is where those meticulous records come in handy. For a medical emergency, you'll need a doctor's statement, medical records, and potentially hospital bills confirming your condition and inability to travel or hunt. For travel disruptions, you'll need airline cancellation notices or official statements from transportation providers. If your outfitter cancels, you'll need their written confirmation. Be prepared to fill out detailed claim forms and provide any additional information the insurance company requests. The process can sometimes be lengthy, so patience is a virtue, but providing all necessary documentation upfront can significantly speed things along. Always keep copies of everything you submit.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.